Basic economic concepts are essential for understanding how the world works. They provide insights into resource allocation and decision-making in everyday life.
By mastering these ideas, you can navigate financial landscapes more effectively. It’s fascinating how these concepts influence everything around us.
Keep reading to discover how these principles can impact your choices and shape economic realities!
What are Basic Economic Concepts?
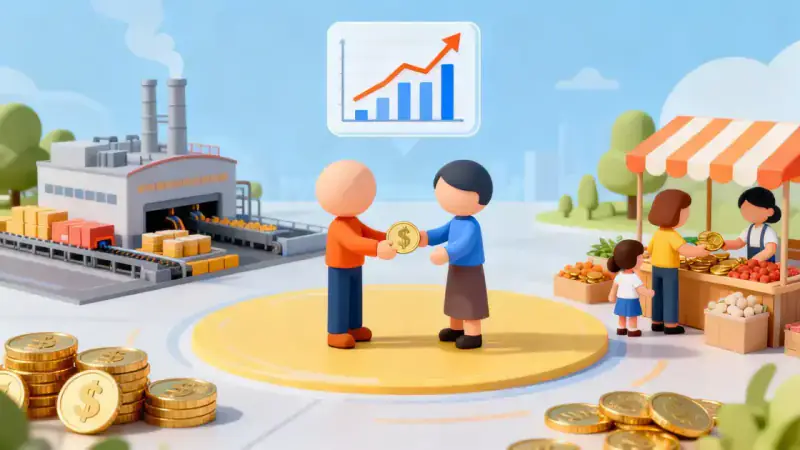
Basic economic concepts are the building blocks that help us understand how economies function. These concepts include ideas like supply, demand, and scarcity, which influence how goods and services are produced and consumed.
Another important aspect is opportunity cost, which means the value of what you give up when making a choice. This helps us make better decisions about where to spend our resources, be it time or money.
Understanding these basic economic concepts is crucial for everyone. They not only explain how markets work but also guide individuals and businesses in making smart choices in their everyday lives.
Importance of Understanding Economics
Understanding economics is crucial because it helps us make informed decisions in our daily lives. When we grasp basic economic concepts, we can better manage our finances, choose careers, and make smart purchases. It empowers us to understand how our choices impact not just ourselves but also our community.
Economics also guides governments and businesses in creating policies that promote growth and stability. By studying trends and patterns, we can predict economic changes, which helps leaders make decisions that improve the quality of life for everyone.
Finally, a solid understanding of economics fosters critical thinking. By evaluating different economic scenarios, we learn to analyze information, weigh options, and draw conclusions. This skill is not just valuable for understanding the economy but is essential for making thoughtful decisions in all areas of life.
Key Principles of Economic Theory
Key principles of economic theory are vital for understanding how economies operate. One fundamental principle is the idea of supply and demand. This principle explains how the availability of goods (supply) and the desire for them (demand) work together to determine prices in the market.
Another important principle is opportunity cost. This means considering what you give up when making a choice. It helps us understand that every decision has a trade-off, reminding us to think carefully about the choices we make.
Additionally, the principle of incentives plays a crucial role. Incentives are rewards or punishments that motivate people to act in certain ways. Understanding how incentives influence behavior helps us predict and explain economic actions and outcomes in society.
Supply and Demand Explained
Supply and demand are fundamental concepts in economics that describe how goods and services are traded in a market. Supply refers to how much of a product is available for sale at different prices. As prices rise, suppliers are usually willing to offer more of the product, meaning supply increases.
demand signifies how much of a product consumers want to buy at various prices. When prices decrease, more people typically want to purchase the item, leading to higher demand. Thus, demand and supply work together to shape market prices.
The interaction of supply and demand determines the equilibrium price, which is where the quantity supplied equals the quantity demanded. At this point, the market is balanced, and there are no shortages or surpluses. Understanding this relationship helps us see how prices fluctuate based on consumer behavior and market conditions.
Microeconomics vs Macroeconomics
Microeconomics and macroeconomics are two important branches of economics. Microeconomics focuses on the individual parts of the economy, such as consumers, households, and businesses. It studies how these entities make decisions about buying, selling, and how they interact in markets.
In contrast, macroeconomics looks at the economy as a whole. This involves analyzing large-scale economic factors like inflation, unemployment, and national output. By examining these elements, macroeconomics helps us understand how economies grow and change over time.
Both microeconomics and macroeconomics are essential for a complete understanding of economic dynamics. While microeconomics helps us understand specific market behaviors, macroeconomics gives us insights into how these smaller actions impact the larger economy. Together, they form a comprehensive view of how our economy functions.
Influence of Economics on Daily Life
Economics influences our daily lives more than we might realize. For instance, our spending habits are often shaped by economic factors. When prices rise, we may decide to buy less of certain products or seek out alternatives, making decisions that directly affect our budgets.
Moreover, economics affects job opportunities and wages in our communities. When the economy is strong, businesses grow, and more jobs become available. Conversely, during economic downturns, job losses can occur, impacting families and local economies.
Lastly, understanding economics helps us make informed choices in various aspects of life, such as savings and investments. Knowledge of economic principles allows us to consider how our actions today will impact our future, ensuring we make better financial decisions in the long run.
How to Apply Economic Concepts
Applying economic concepts in everyday life can help make better decisions and manage resources effectively. For instance, understanding supply and demand can guide your purchasing choices. When consumers know when to buy based on price changes and product availability, they can save money and make smarter choices.
You can also apply the idea of opportunity cost when deciding how to spend your time and money. By thinking about what you give up when you choose one option over another, you can prioritize activities and transactions that offer the greatest benefit or value.
Finally, looking at incentives in your own life can help you understand what motivates your choices. Whether it’s budgeting your allowance or deciding which projects to take at work, recognizing how different factors influence your decisions can enhance your overall economic awareness and lead to better outcomes.