Purchasing power explained helps you understand how much your money can buy in today’s economy. It is crucial for making informed financial choices that affect your daily life. Understanding purchasing power can empower you to navigate the market smartly.
Many factors influence this concept, like inflation and wage changes, which can leave individuals feeling squeezed or relieved. This knowledge is vital in making strategic purchases and investments based on your finances.
Unlock the mysteries of purchasing power and see how it shapes your financial landscape. Keep reading to discover how this understanding can enhance your financial well-being!
What is Purchasing Power?
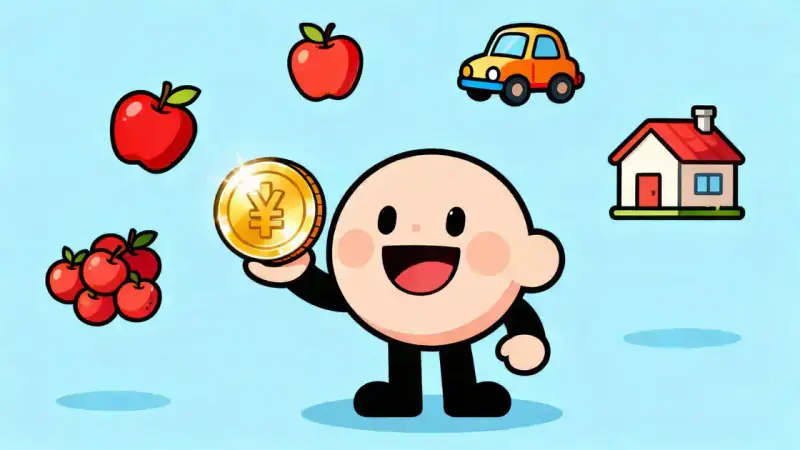
Purchasing power refers to the amount of goods or services that a unit of currency can buy. It helps us understand how our money works in the real world. When prices rise, our purchasing power goes down, meaning we can buy less with the same amount of money.
Many factors can affect purchasing power, such as inflation, income changes, and economic conditions. When people earn more money, their purchasing power can increase, allowing them to buy more. However, if prices rise faster than wages, purchasing power decreases.
Understanding purchasing power is important for making smart financial decisions. It helps you know how far your money will go when shopping or planning expenses. Being aware of this concept can guide you in budgeting and saving effectively for the future.
Factors Affecting Purchasing Power
Several factors affect purchasing power, with inflation being one of the most significant. When the prices of goods and services rise, each dollar buys fewer items. This means that, over time, people may find that their money does not stretch as far as it once did. It’s crucial to understand how inflation can erode purchasing power and impact daily life.
Another factor is changes in income levels. When a person’s income increases, their purchasing power can improve, allowing them to buy more. However, if wages do not keep up with rising prices, people might feel like they have less money to spend. Job stability and opportunities for raises also play a role in this equation.
Lastly, economic conditions, such as recessions and booms, influence purchasing power. During a recession, people may lose jobs or face cutbacks in their hours, leading to reduced buying power. Conversely, in a strong economy, more jobs and higher wages can boost purchasing power, giving people greater freedom in spending and saving.
Inflation and Purchasing Power
Inflation is the rate at which prices for goods and services increase over time. When inflation rises, it impacts purchasing power because each dollar you have can buy less than before. For example, if inflation is high, you may notice that the groceries and clothes you usually buy cost more than they did last year.
This relationship between inflation and purchasing power is crucial for understanding personal finances. If your wages do not increase to match inflation, you are effectively losing purchasing power. This means you might have to cut back on spending or find ways to earn more to maintain your standard of living.
Keeping an eye on inflation helps consumers make better financial choices. Tracking inflation rates can inform decisions on saving, investing, and spending. By understanding how inflation affects purchasing power, you can plan ahead and protect your finances from being eroded over time.
How to Measure Purchasing Power
Measuring purchasing power is an important step in understanding how far your money can go. One common method is to look at the Consumer Price Index (CPI). The CPI tracks the average change in prices over time for a basket of goods and services. By comparing the CPI from different years, you can see how inflation affects what you can buy.
Another way to measure purchasing power is by looking at income figures and how they change over time. If wages increase but prices increase at a faster rate, your purchasing power decreases. Calculating the real income, which adjusts for inflation, helps give a clearer picture of how much purchasing power you truly have.
Additionally, using purchasing power parity (PPP) can help compare the cost of living between different regions. This method estimates how much money you need in one place to buy the same items you could get for less in another area. Understanding these measurements can help you make better spending and saving decisions.
Purchasing Power Parity Explained
Purchasing Power Parity, or PPP, is an economic theory that helps compare the value of currencies in different countries. It suggests that in an ideal world, you should be able to buy the same amount of goods in different countries using different currencies. This means that, according to PPP, the price of a specific item in one country should be equal to the price of that same item when converted to another country’s currency.
To understand PPP better, consider how much a basket of common goods costs in two different countries. If the basket costs $100 in the United States and is equal to €90 in Europe, PPP can help you see if the euro is undervalued or overvalued. This comparison can also aid in understanding cost of living differences and help travelers budget better.
While PPP provides a useful way to compare economic situations, it does have limitations and does not account for factors such as taxes and transportation costs. Despite this, it remains a valuable tool for economists and individuals to understand currency values and purchasing power across the globe.
Effects of Purchasing Power on Economy
The effects of purchasing power on the economy are significant and wide-ranging. When purchasing power increases, people can buy more goods and services, which boosts demand. This increased demand can lead to business growth, more jobs, and a stronger economy overall. People are more likely to spend money when they feel they can afford to buy what they need.
Conversely, when purchasing power decreases, consumers tend to cut back on spending. This drop in demand can hurt businesses, leading to slower growth and potential layoffs. If many people suffer from decreased purchasing power at once, it can lead to a recession, where economic activity slows down significantly.
Moreover, purchasing power can affect government policies as well. When citizens struggle with lower purchasing power, governments may need to intervene through policies like wage increases or subsidies. These actions aim to support consumers and encourage spending, which, in turn, can help stimulate the economy.
Tips to Improve Your Purchasing Power
Improving your purchasing power begins with smart budgeting. By creating a budget, you can track your income and expenses more effectively. This helps you to identify where your money goes and allows you to cut unnecessary costs. The more you save, the better your purchasing power will be, as you can afford to buy more or invest for the future.
Another tip is to look for ways to increase your income. This could mean asking for a raise, finding a higher-paying job, or even starting a side hustle. By boosting your earnings, you can enhance your purchasing power, giving you more freedom in how you spend or save your money.
Lastly, being mindful of inflation is essential. When you know how inflation affects prices, you can make informed decisions about when to buy certain items. Waiting for sales or purchasing in bulk can also help stretch your dollars further, making your spending more effective and improving your overall purchasing power.